Client story · Insurance

A clearer path through contractor insurance.

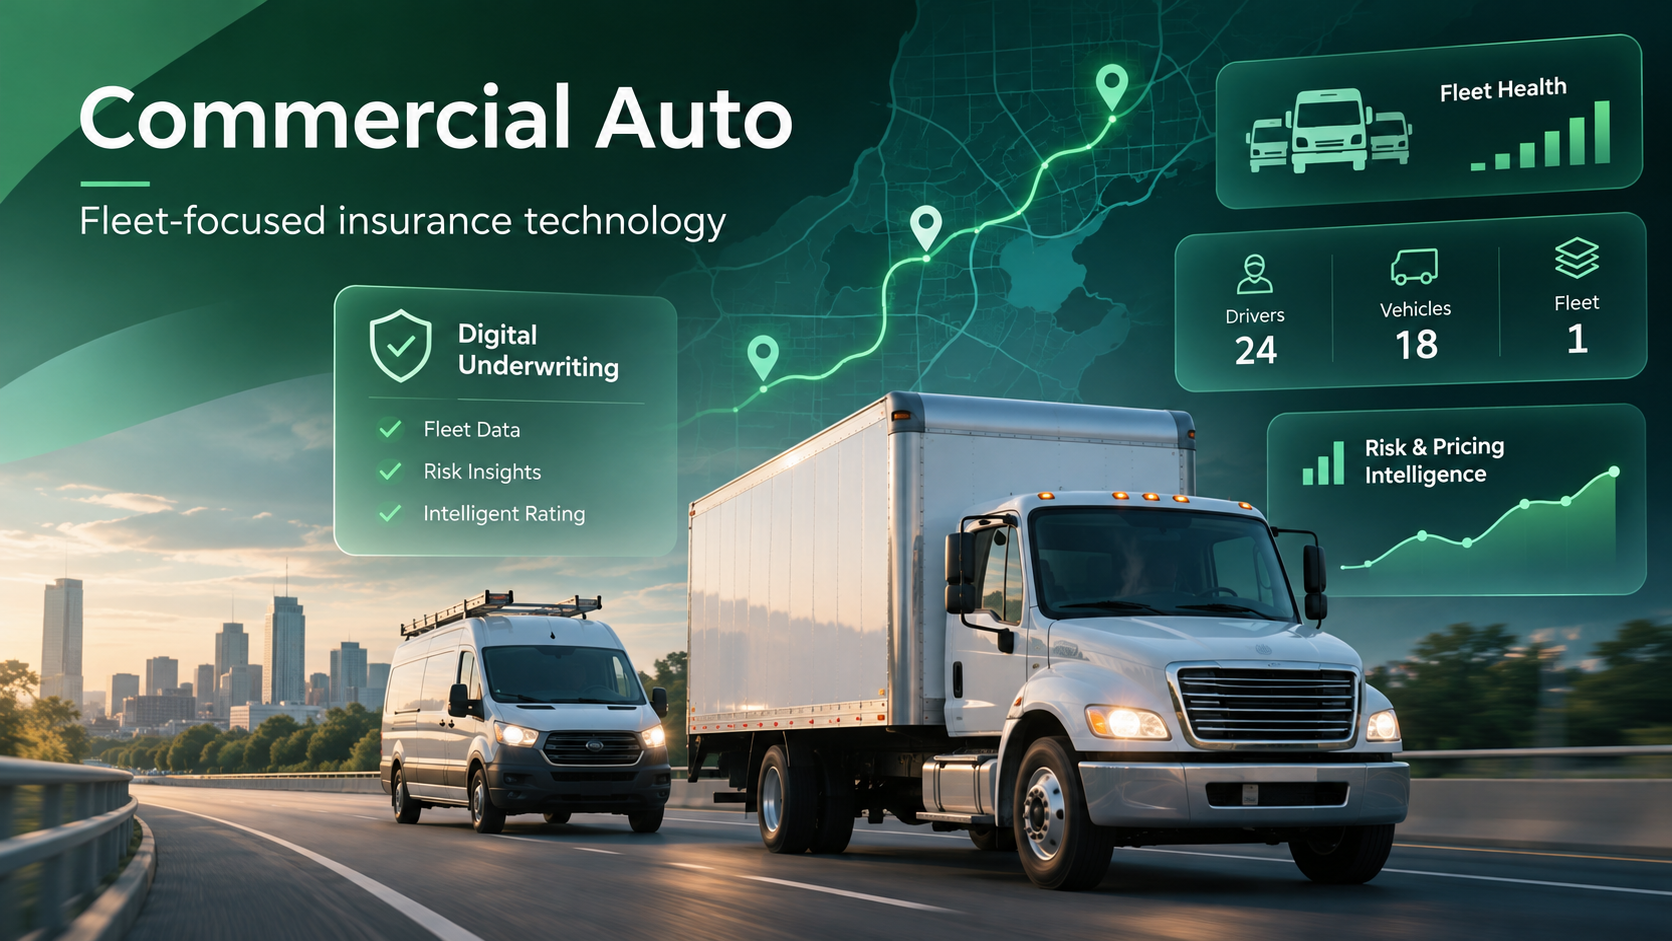
Contractor insurance MGA and E&S broker founded in 2004, writing GL, excess, workers’ compensation, inland marine, BOP and pollution liability for brokers nationwide through its own online rater — the Shield Insurance Rater, credited in the application as “Powered by Jaspar Technologies.” Shield also offers Commercial Auto for eligible business fleets.

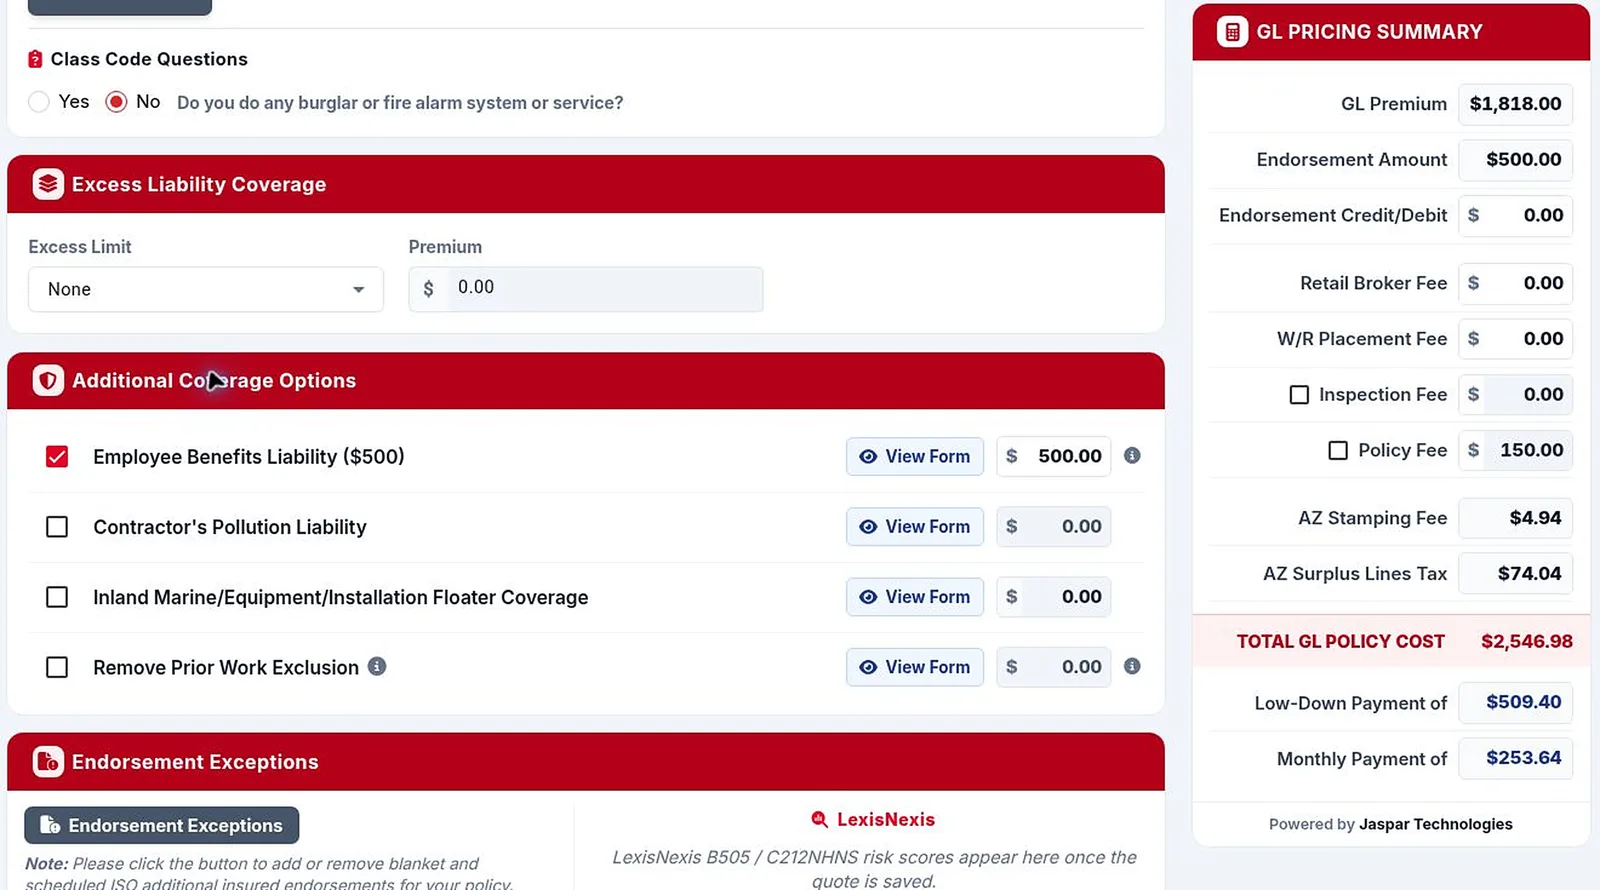
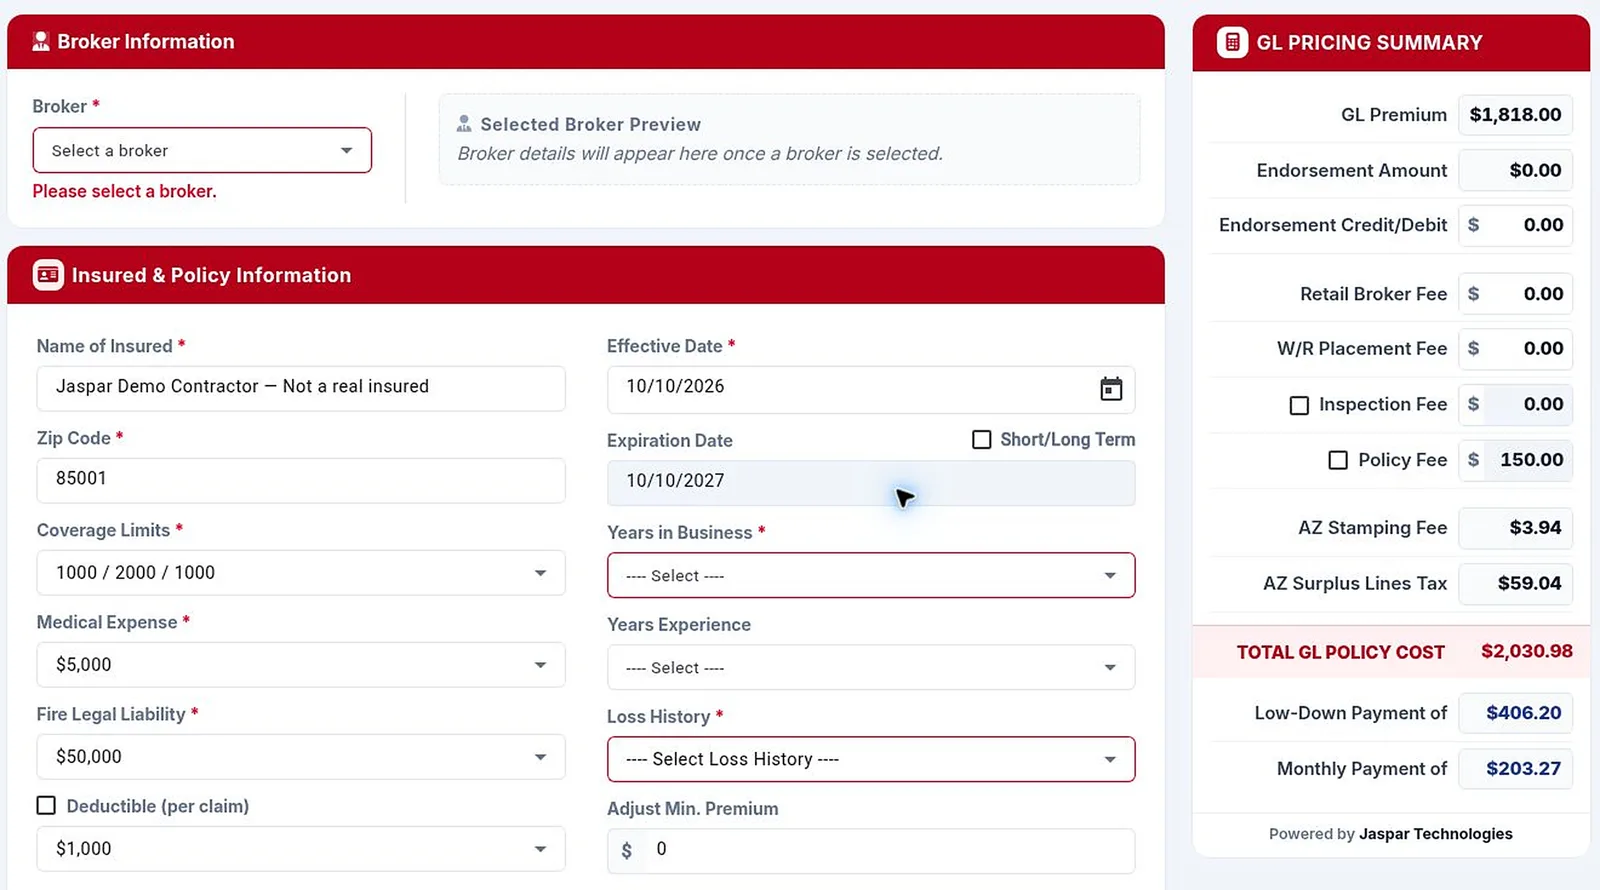
Shield Insurance Rater GL form beside the GL Pricing Summary, which reads “Powered by Jaspar Technologies”
Staging · fictional data
Construction professionals reviewing work at a scaffolded building site
Powered by Jaspar Technologies
Client
Shield Commercial Insurance Services
Sector
Commercial contractor insurance
Location
Palm Desert, California
Jaspar’s work
Shield Insurance Rater · Commercial Auto rater
Demonstration
Project tour · 1:34
The business

Understanding Shield.

Shield Commercial Insurance Services is a Palm Desert, California MGA, E&S broker and MGU founded in 2004. It writes General Liability, Excess, Workers’ Compensation, Inland Marine, BOP and Contractors Pollution Liability for retail brokers nationwide, rating, quoting and binding through its own online platform rather than direct to the public. Shield also offers a Commercial Auto program for eligible business fleets in 25 states.

Founded
2004
Headquarters
Palm Desert, California
Business model
MGA, E&S broker and MGU — broker-only, not direct to the public.
Coverage lines
General Liability, Excess, Workers’ Compensation, Inland Marine, BOP and Contractors Pollution Liability, plus Commercial Auto for eligible business fleets.
Distribution
Retail brokers nationwide rate, quote and bind through Shield’s own online platform.
Corporate family
Part of NSM Insurance Group; since 2025 within Novacore, NSM’s former U.S. commercial division.
Shield / At a glance

Distinct insurance programs. Product-specific underwriting.

Figures below come from Shield’s own published product and eligibility pages — the kind of operating detail a quoting platform has to hold onto without slowing a broker down.

Founded2004

Palm Desert, California MGA, E&S broker and MGU.

Contractor programs7 lines

GL, excess, workers’ comp, inland marine, BOP and pollution liability, each with its own eligibility rules.

Eligible trades40+

From general contractors and roofers to landscapers, electricians and pollution-exposed trades.

Excess capacity$5M

Follow-form excess and umbrella limits of up to $5M layered on top of the underlying GL policy.

01

Program-specific eligibility

Each contractor product — small or large GL, excess, workers’ comp, inland marine, BOP or pollution liability — carries its own eligible trades and exclusions, from a height limit on large-contractor GL to standard carve-outs for asbestos abatement, blasting and crane work over 20 feet.
02

Underwriting rules as product logic

Rules like the Roofing Operations Warranty for open-roof and torch-down work, a subcontractor-cost credit capped at 50% of gross receipts, and a resume requirement for ventures under three years old belong in the product model, not just underwriter memory.

03

Broker self-service

Brokers rate, quote and bind directly through Shield’s own online rater, with a same-day target on new submissions. The interface needs to carry required documents and outstanding conditions through to bind.

The difficult cases

Where contractor rating gets specific.

A happy-path quote is only one part of the problem. Variation, referral and correction paths deserve equal attention across Shield’s contractor programs.

Rules and effective dates

Large-contractor GL caps height at 50 feet or five stories; small-contractor GL excludes multi-story commercial work past three stories. Each limit needs a traceable rule version.

Reference calculations

Boundary cases include open-roof and torch-down roofing under the Roofing Operations Warranty, and the flat $1,000 inland-marine deductible with no coinsurance.

Referral and authority

A paper contractor, a venture under three years, or solar work needing five years of loss runs should route to a named underwriter with the reason for review visible.

Changes after submission

Shield targets a 24–48 hour endorsement turnaround and marks a request “Holding” while awaiting carrier approval — a status that belongs in the broker’s view too.

What Jaspar Technologies built

The Shield Insurance Rater.

One application where appointed brokers start a contractor submission and watch it priced as they work — from the coverage-line launcher to a quote record that keeps every related document together. The rater carries the credit line “Powered by Jaspar Technologies” in its own interface. Jaspar also developed a separate Commercial Auto rating experience for Shield, extending its work across distinct commercial insurance products.

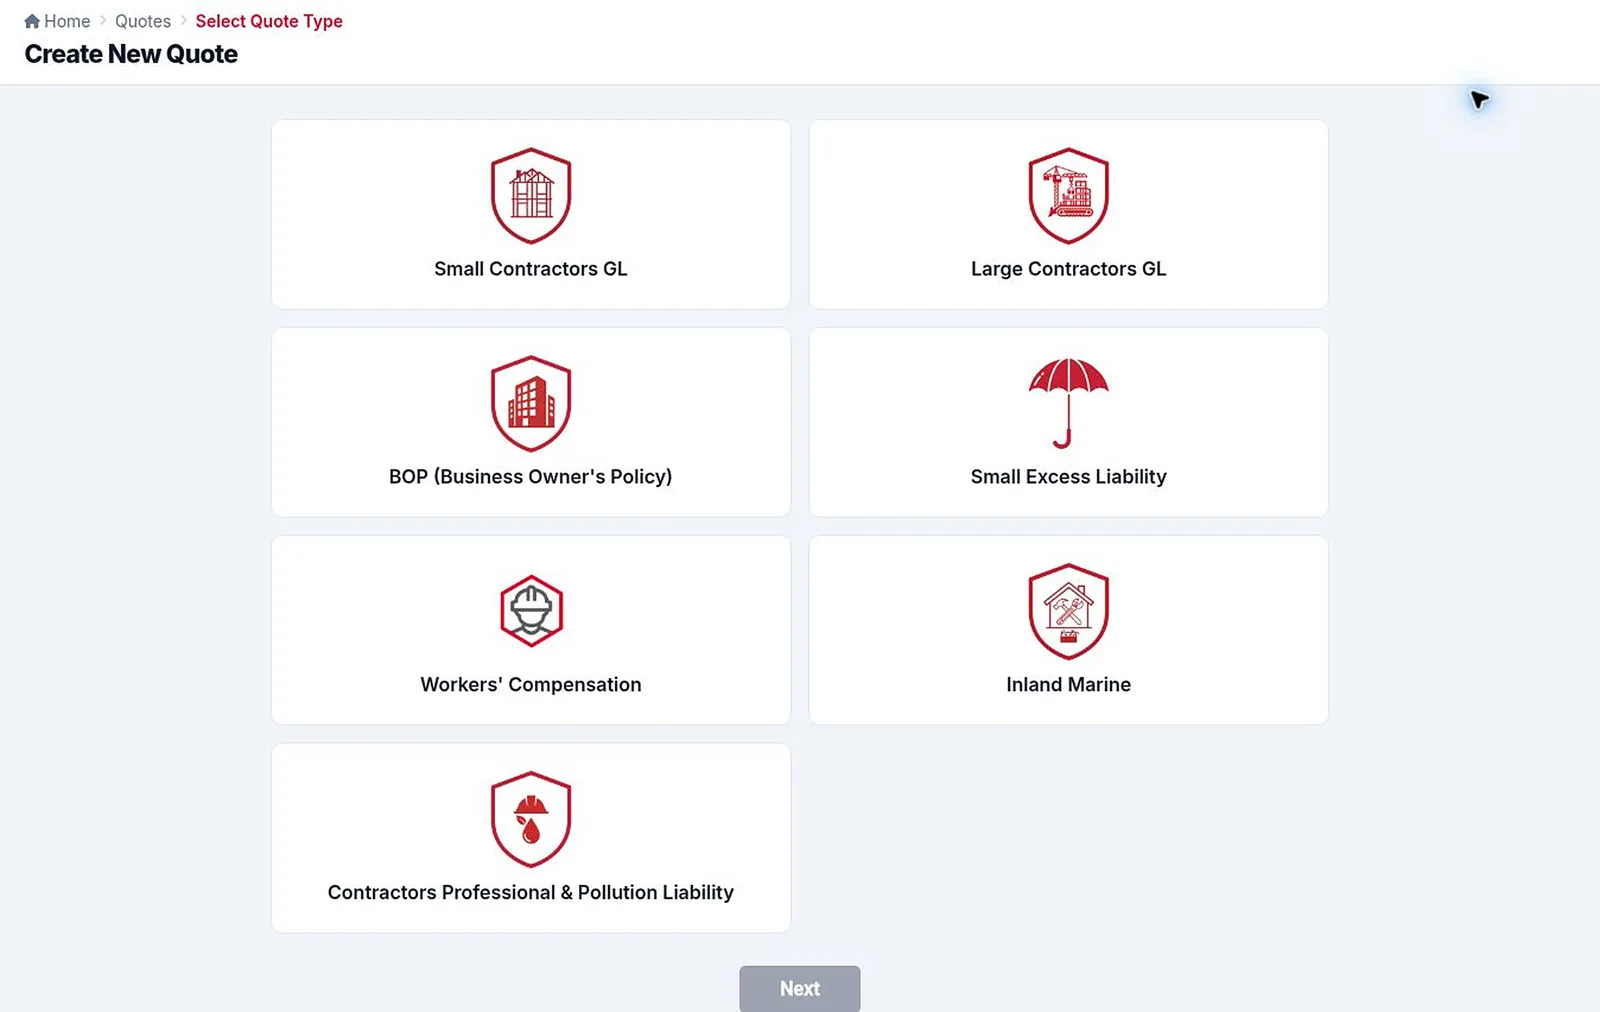
  • Seven coverage lines, one launcher. Small and Large Contractors GL, BOP, Small Excess Liability, Workers’ Compensation, Inland Marine, and Contractors Professional & Pollution Liability.
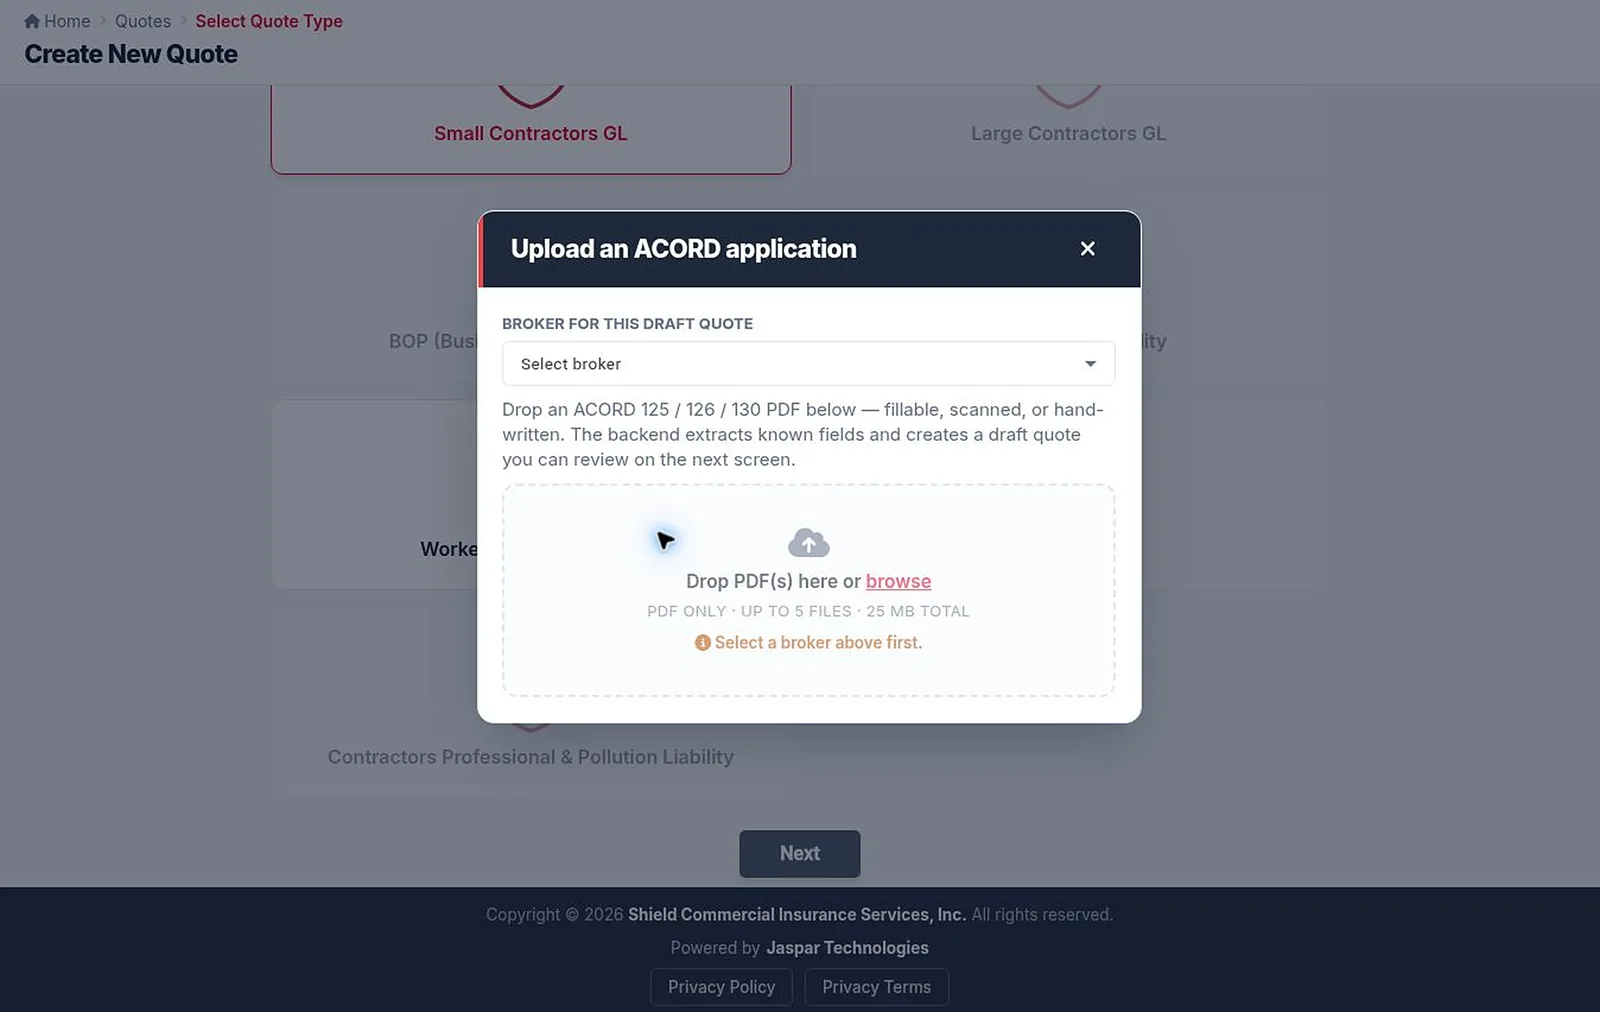
  • Manual entry or ACORD upload. A submission can be keyed in by hand or started from an ACORD 125, 126 or 130 upload once a broker is selected.
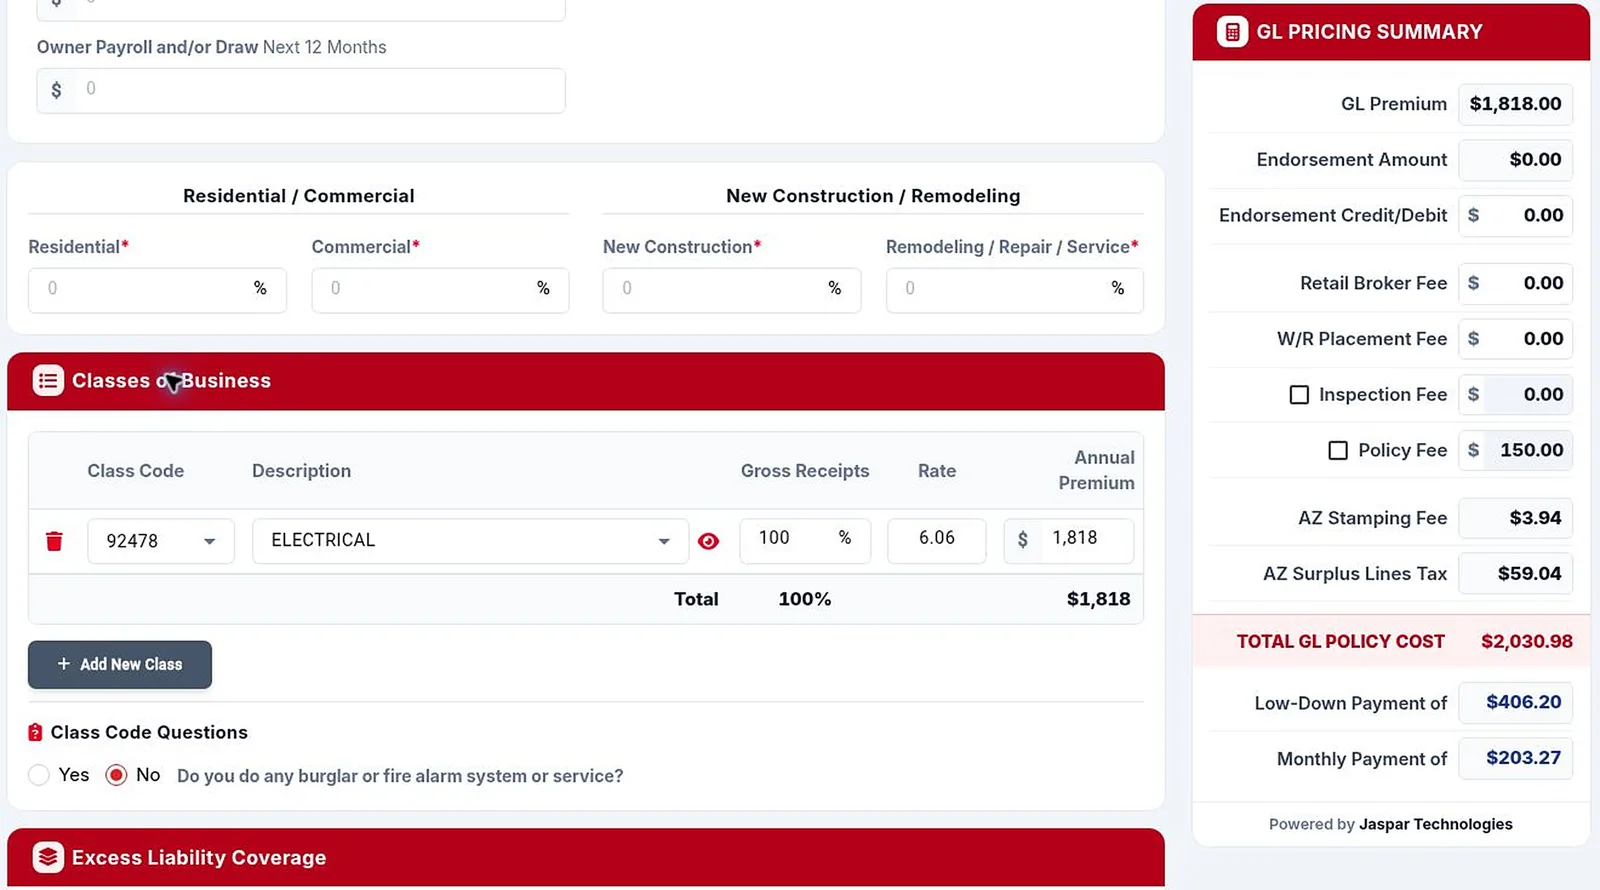
  • Class-based GL rating. Choosing a trade fills class code, rate and annual premium; a ZIP code sets the state and its fee and tax lines.
  • Live recalculation. Optional coverages such as Employee Benefits Liability recalculate endorsement, fees, tax, total and payments while the base premium holds.
  • Line-specific applications. Workers’ compensation tracks required answers, small excess builds on the primary GL policy and inland marine schedules equipment item by item.
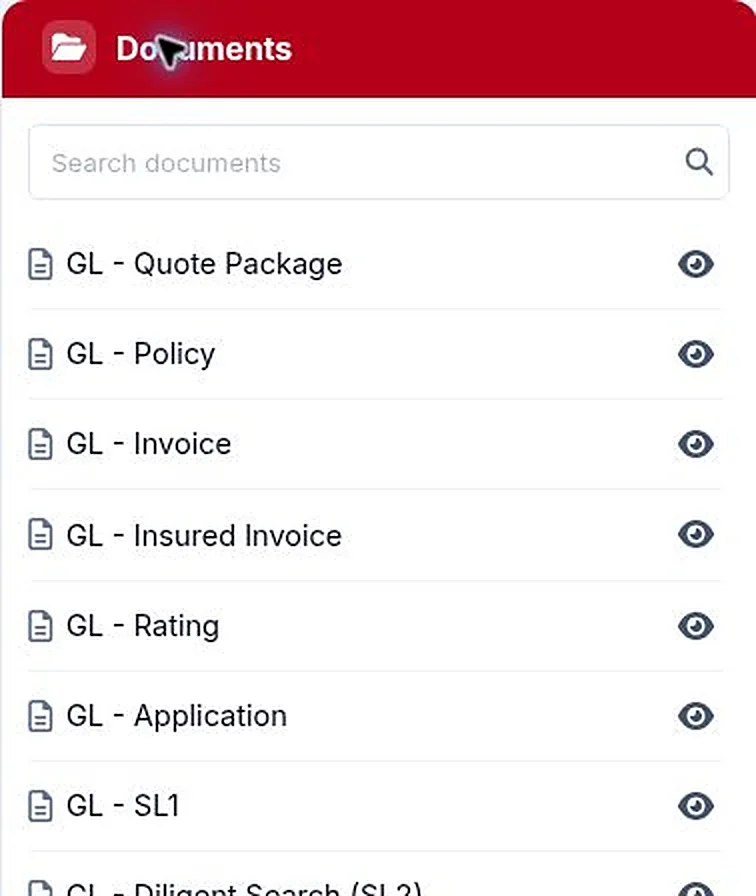
  • A connected quote record. Quote summary, policy, underwriting, insured, fees and IRPM, documents, claims, audits, inspections and history.

Shown with fictional data in a staging environment

Explore our insurance technology practice
Classes of Business table with class code, rate and annual premium beside the GL pricing summary
Additional rating experience / Commercial Auto

A separate rater for Commercial Auto.

Jaspar Technologies developed a dedicated Commercial Auto rater for Shield, extending its insurance technology work beyond contractor General Liability. The separate rating experience supports Shield’s Commercial Auto offering, which has its own fleet, driver, vehicle and underwriting requirements.

Different insurance products require different rating experiences. Our work with Shield demonstrates how specialized insurance software can be developed around distinct commercial insurance programs.

The insurance requirements behind the experience.

Shield’s published program requirements, summarized from its 2026 Commercial Auto Product Guide.

01

Fleet and business profile

Shield’s published Commercial Auto program targets established businesses with fully owned or leased fleets of 5 to 50 power units, primarily operating within local and intermediate radii.

02

Drivers and vehicles

The program requires driver and vehicle information, including driver lists, motor vehicle records, vehicle schedules and stated values where applicable.

03

Underwriting documentation

Commercial Auto submissions have product-specific requirements, including loss-run documentation, location information and Shield Auto supplemental questions.

Shield’s 2026 Commercial Auto Product Guide lists availability in 25 US states for eligible contractor and commercial business classes.

Explore Shield Commercial Auto (opens in a new tab)
Workflow · product experience

The anatomy of a contractor quote.

Six stages of contractor quoting in the Shield Insurance Rater, from the project tour and shown with the staging screens it uses. All data is fictional; no quote was saved or bound.

01

Choose one of seven coverage lines.

Every quote begins in a launcher with a card for each Shield program — from Small Contractors GL to Contractors Professional & Pollution Liability.

Create New Quote launcher with seven Shield coverage-line cards
02

Select the broker, then key in or upload.

A submission can be entered by hand or started from an ACORD 125, 126 or 130 application upload — once a broker is selected.

ACORD application upload path that asks for the broker first
03

Rate by contractor class.

In Small Contractors GL, a ZIP code sets the state and the stamping fee and surplus-lines tax lines follow. Choosing the contractor’s class fills class code, rate and annual premium, with fees, total cost and payment options beside the form.

Classes of Business entry with class code, gross receipts, rate and annual premium
04

Recalculate as coverage changes.

Adding an optional coverage such as Employee Benefits Liability recalculates endorsement, fees, tax, total and payments — while the GL base premium holds.

Optional coverage selections in the Shield GL application
GL pricing summary after recalculation with total cost, low-down payment and monthly payment
05

Follow each line’s own application.

Each coverage line has its own application, built around what that product needs.

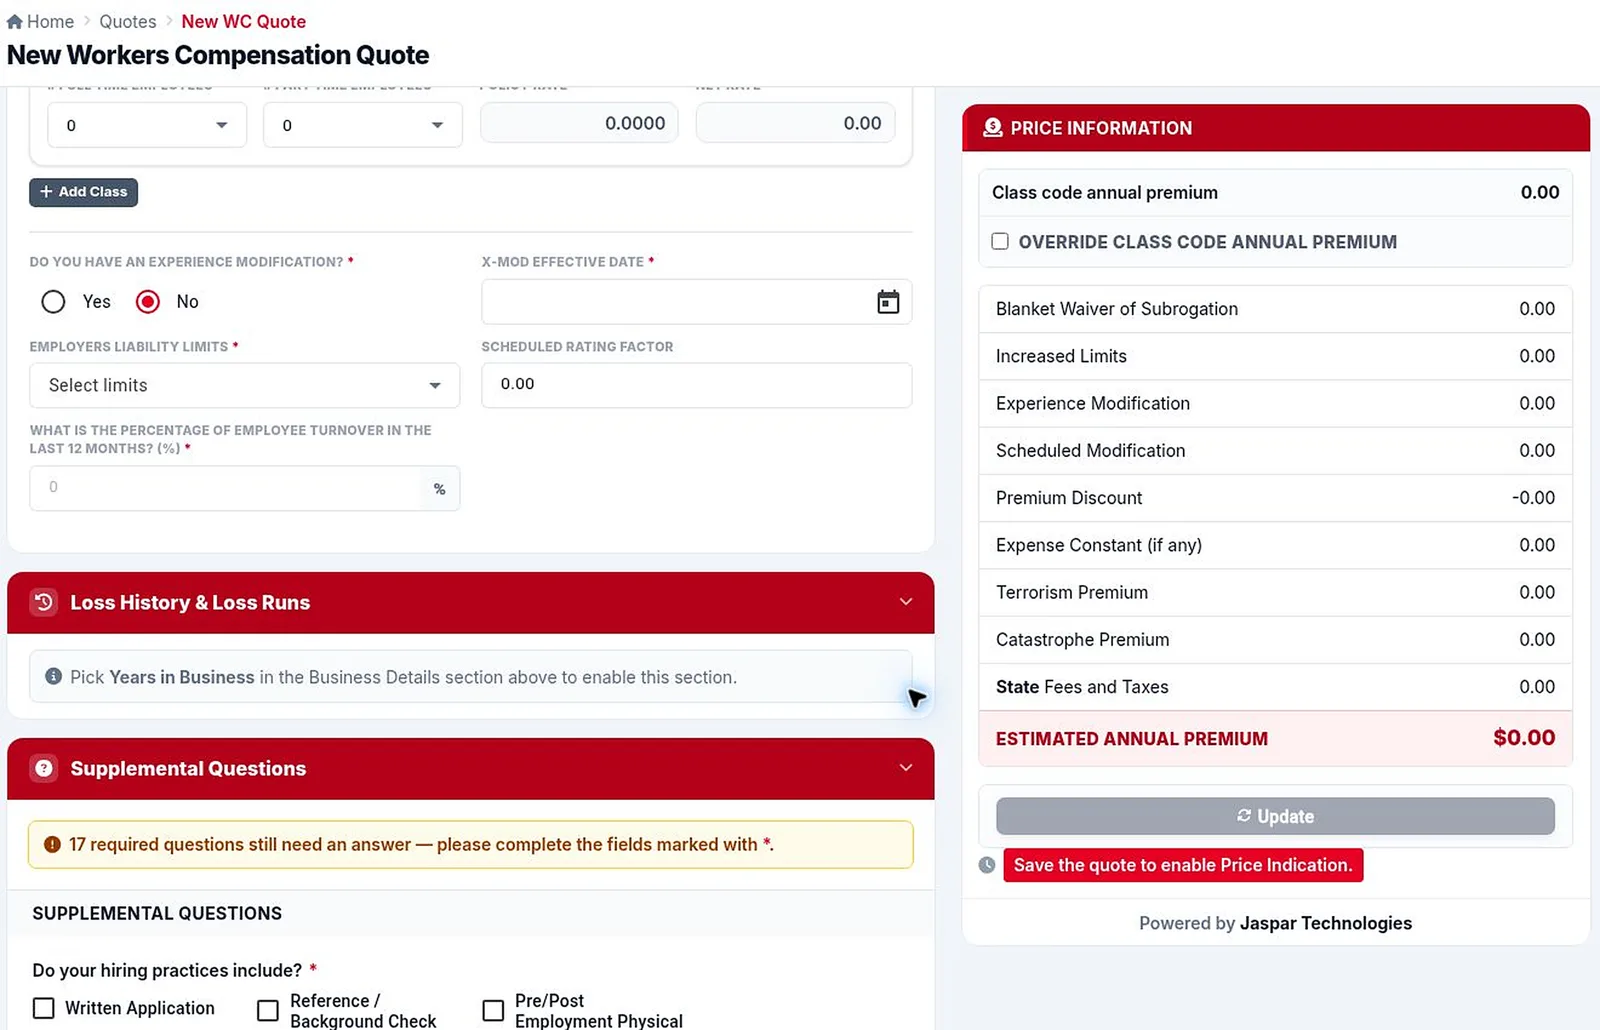
  • Workers’ compensation tracks every required answer, and price indication waits for a saved quote.
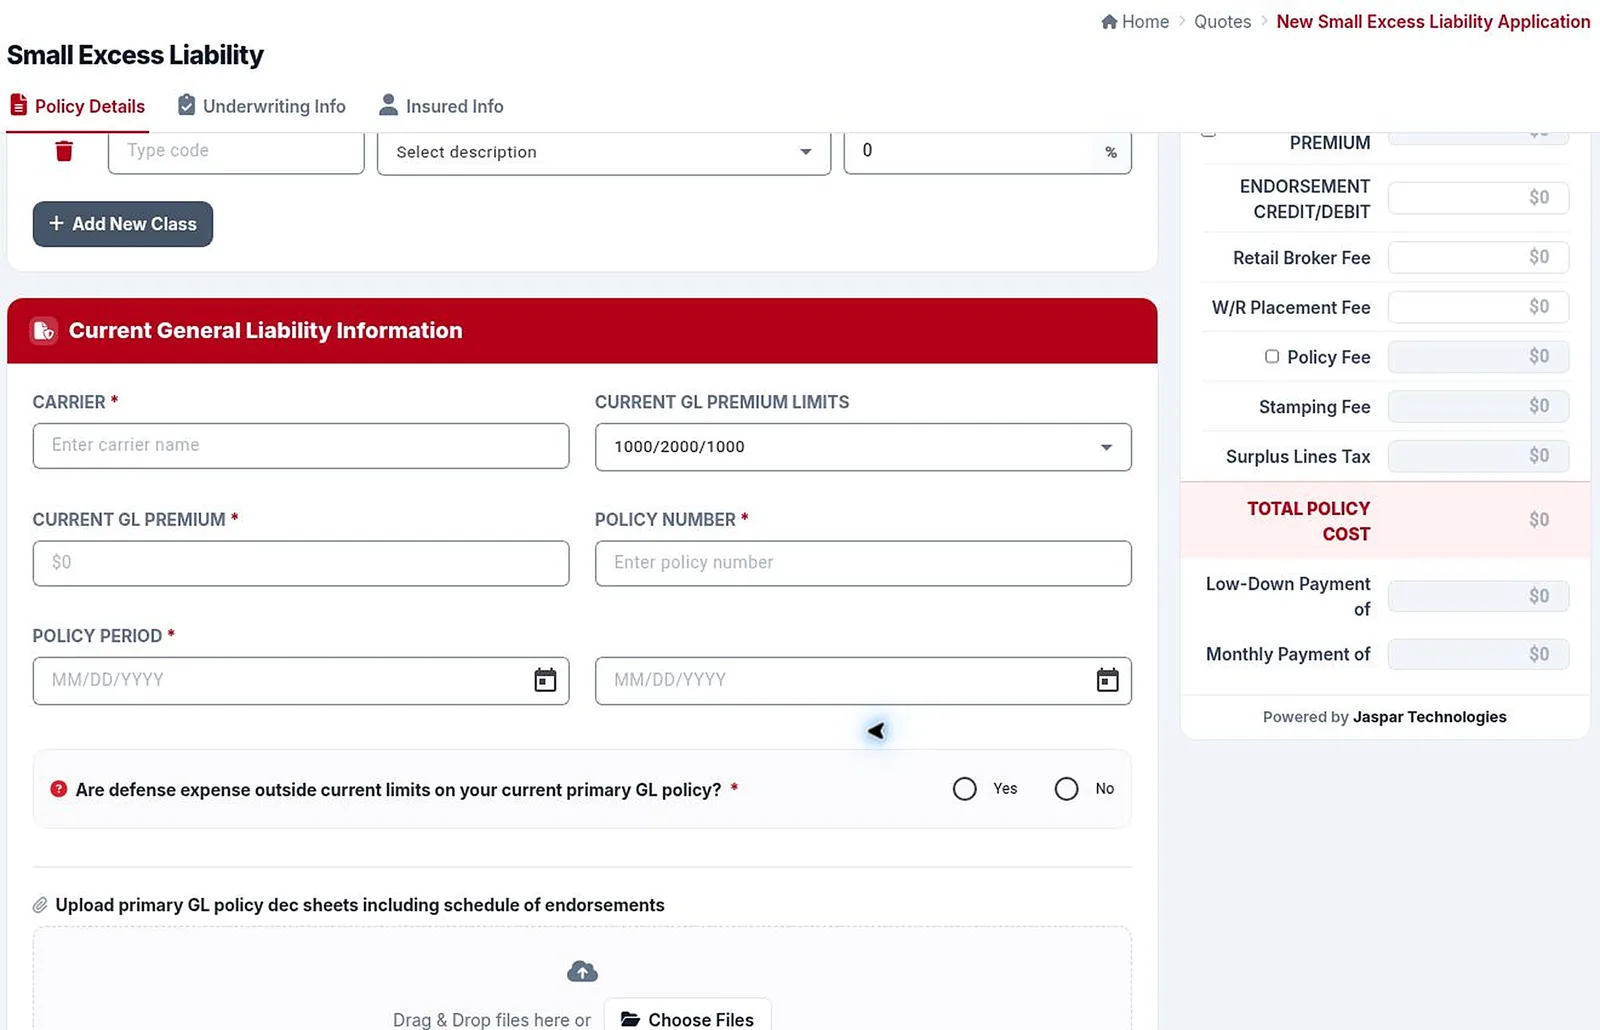
  • Small excess liability is requested against the contractor’s current primary GL policy.
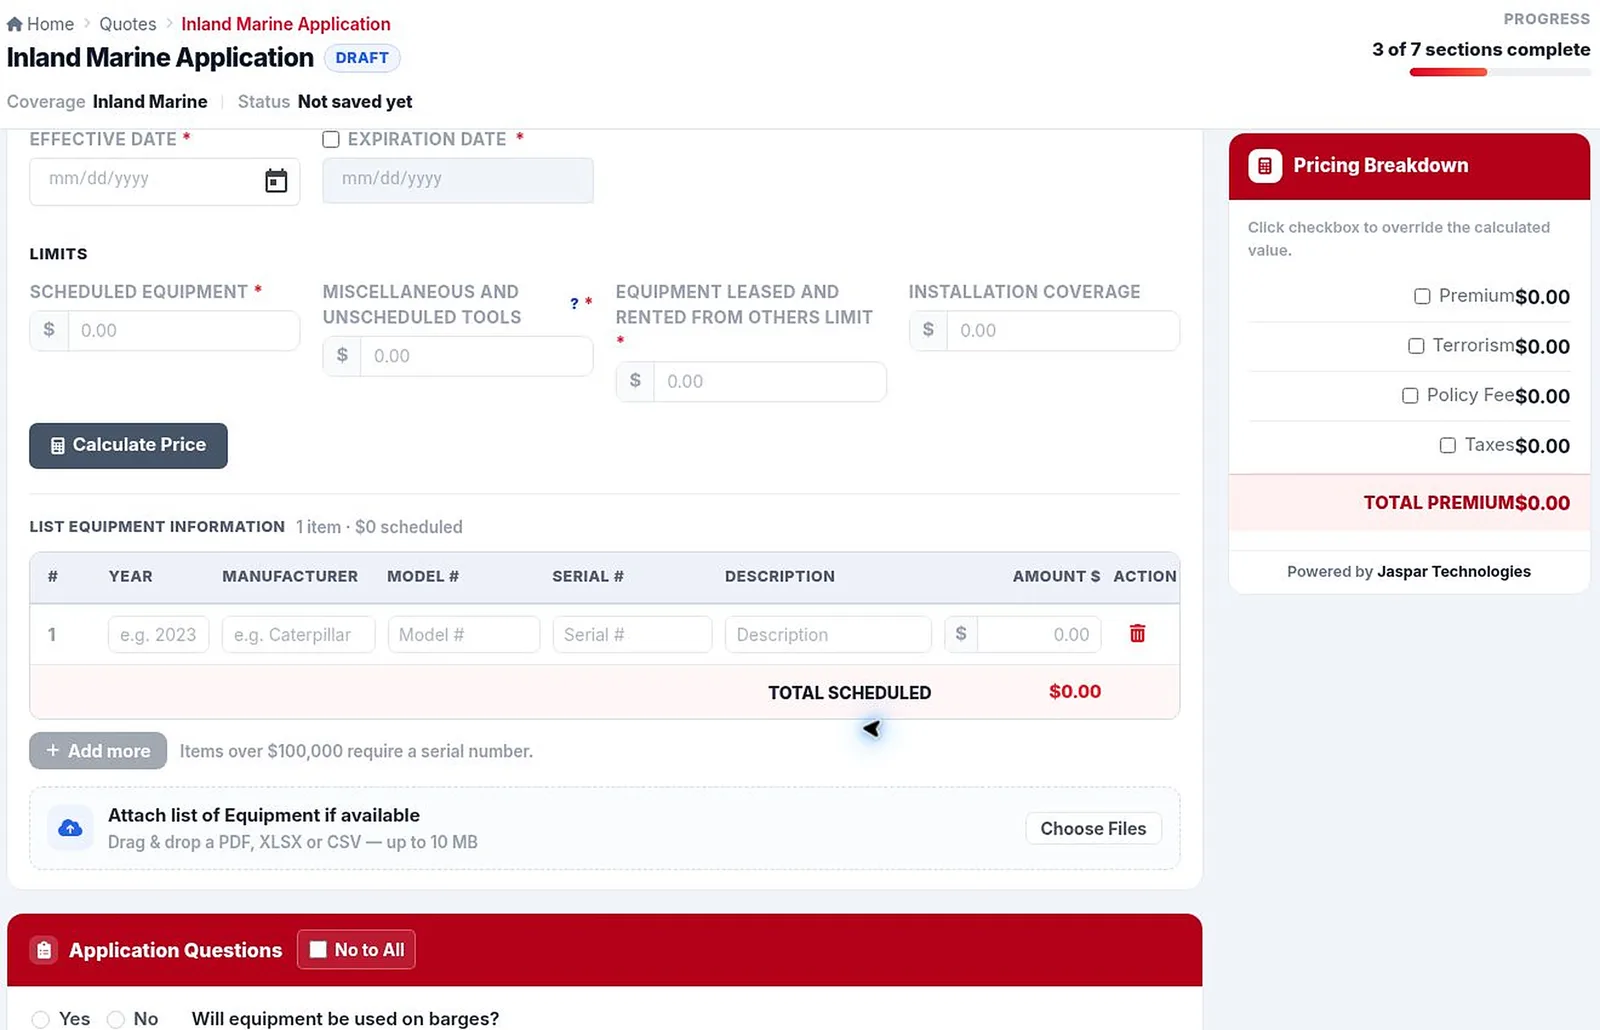
  • Inland marine schedules equipment item by item, with serial numbers required for high-value items.
Workers’ compensation application with required-question tracking
Inland marine equipment schedule with item-by-item entries
06

Keep the quote record together.

Around each quote, the workspace keeps the quote summary, policy, underwriting, insured, fees and IRPM, documents, claims, audits, inspections and history in one record.

Small excess liability application referencing the current general liability policy
Document categories attached to a Shield quote record
Project tour

Shield — Insurance Rater Demonstration

A tour of the rater’s staging environment: the seven-line launcher, ACORD intake, class-based rating and recalculation, line-specific applications and the connected quote record.

Start a conversation

Have a similar business challenge?

Talk to us about the users, workflows and systems your project needs to support. We can help turn that context into a practical scope.